In the Loop – October 30, 2026
“In The Loop” is designed to give you a short update reflecting major developments, earnings, and investment trends across some core Equity Income and Growth holdings. All clients should be aware that individual buy/sell recommendations will be conveyed directly to you on an individual basis. Have a great weekend.
What a week on Wall Street! Investors were confronted with a powerful combination of corporate earnings, a Federal Reserve decision, stronger economic growth, persistent inflation, and renewed questions about the enormous amount of money being invested in artificial intelligence. The economy continues to demonstrate remarkable resilience, with third-quarter GDP expanding at an annualized 3.4%, while consumer spending remains supportive. However, inflation is proving more difficult to contain, with the Fed’s preferred PCE inflation measure running at 3.6%. The Federal Reserve left short-term interest rates unchanged at 3.75%–4.00%, reinforcing the reality that stronger economic growth and stubborn inflation may keep interest rates elevated longer than investors had anticipated.
Perhaps the biggest story this week was the market’s changing attitude toward artificial intelligence. Earnings from Alphabet, Microsoft, and Amazon demonstrated that AI investment remains substantial, but investors are becoming increasingly concerned about how quickly these expenditures will translate into earnings and free cash flow. Alphabet’s disappointing results triggered a sharp selloff, while Amazon’s continued spending weighed on sentiment. The market is no longer rewarding companies simply for announcing larger AI investments; it is demanding evidence of an attractive return on that capital. This distinction is important because the companies spending hundreds of billions of dollars building AI infrastructure are not necessarily the same companies receiving that money.
Meanwhile, rising energy prices and elevated long-term Treasury yields continue to complicate the inflation outlook. Oil prices above $100 per barrel are putting additional pressure on transportation, manufacturing, and household budgets. Although Treasury yields retreated late in the week, borrowing costs remain restrictive for many businesses and consumers. This creates an unusual environment: an economy growing at a healthy pace, corporate America investing aggressively, and a bond market still concerned about inflation, government borrowing, and the supply of new debt.
Our perspective remains focused on the distinction between our Speed 1 and Speed 2 economies. Speed 1 companies—those supplying power, electrical infrastructure, semiconductors, memory, networking, and the physical equipment required for domestic investment. Speed 2 companies, particularly those dependent on distant earnings expectations and higher valuations, face greater scrutiny when interest rates remain elevated. This week’s volatility reminds us that even strong secular investment themes experience corrections. We believe the opportunity remains substantial, but balance-sheet strength, free cash flow, pricing power, and the ability to convert growing demand into profits will increasingly separate the winners from the losers.
For investors, the message is straightforward: We are not abandoning the AI investment theme or our broader U.S. resiliency strategy. We are becoming more selective about where capital is deployed. In an environment of strong economic growth, elevated interest rates, and increasing market dispersion, owning the right businesses at reasonable valuations matters more than simply owning the most popular stocks. The Bull Market is not over. We do not see any signs of a recession nor a Fed ready to aggressively hike rates. The Fear of Missing Out (FOMO) is still alive and Yields on the Long-End have moderated this week.
As of October 30, 2026, I would highlight three distinct groups: bond proxies benefiting from defensive rotation (DUK, NEE, PG), companies with considerable cash on their balance sheets (BRK.B, AAPL), and businesses generating substantial free cash flow (CVX, XOM).
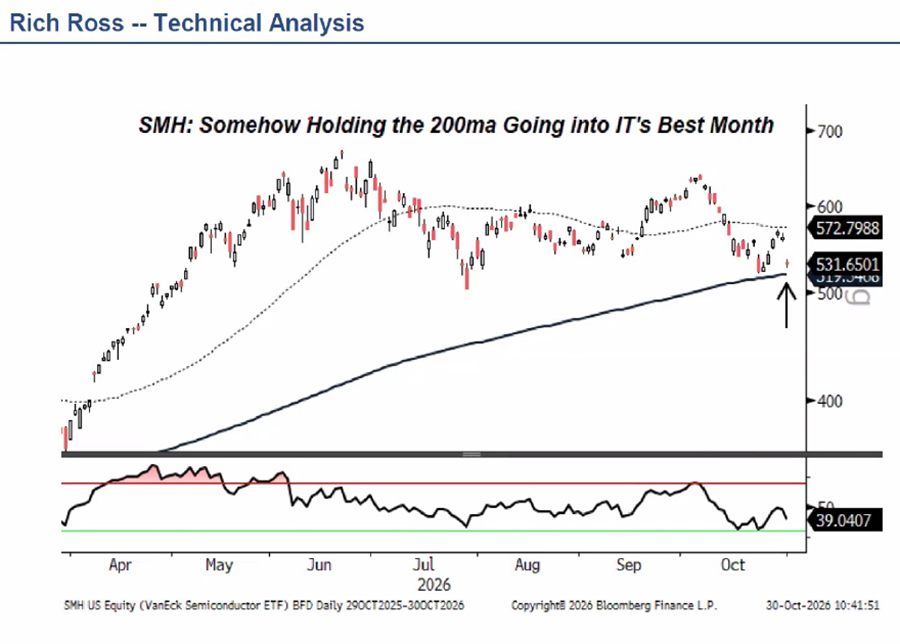
Semiconductor stocks have historically been among the most important leading indicators of both the stock market and the economic cycle. The SOX (Semiconductor Index) is oversold and bottoming at its 200MDA dating back to July. This is a good set-up going into the best months of the year. We are following NVDA, TSM, AMD, MRVL and MU. If the Semi Index holds and reverses, these companies are likely to rally into year-end.
Commercials are also over…
Politics matters for stocks short-term. However, I’m willing to debate on how much they matter long-term. Either way, please Vote on Tuesday!
Happy Halloween!
Formidable Asset Management (“Massey Romans Capital”) is an investment adviser registered under the Investment Advisers Act of 1940. The information presented in the material is general in nature and is not designed to address your investment objectives, financial situation or particular needs. Prior to making any investment decision, you should assess, or seek advice from a professional regarding whether any particular transaction is relevant or appropriate to your individual circumstances. Although taken from reliable sources, the Firm cannot guarantee the accuracy of the information received from third parties.
The opinions expressed herein are those of the Firm and may not actually come to pass.Author
Paul MasseyRelated posts
In the Loop – February 27, 2026
The calm at the index level hides strong currents beneath the surface. The S&P 5
In the Loop – July 24, 2026
98 S&P 500 companies have reported 2Q results. Reported Sales growth has been +1
In the Loop – July 3, 2026
Tomorrow, America celebrates its 250th birthday. As I was thinking about what to